FFieldVisit

Follow-ups

Repayment Follow-ups in Mumbai

Communicating the client's repayment request and recording the borrower's response.

Quick answer

Repayment Follow-ups — communicating the client's repayment request and recording the borrower's response.

What our team checks

  • Due amount and date communicated
  • Borrower response recorded
  • Reason for delay captured
  • Payment options explained
  • Follow-up date set

What you receive

  • Follow-up log
  • Response summary
  • Promise list
  • Escalation cases
Repayment Follow-ups field visit

Share these to get started

  • Case allocation file
  • Client authorisation letter
  • Approved communication script
  • Payment channel details

Visit protocol

How a repayment follow-up visit runs

Five phases on the day, from address review to a supervisor-reviewed submission across our coverage areas. The 5-point checklist is fixed before dispatch so each visit records the same fields.

  1. 1

    Before the visit

    Address review & routing

    Allocated cases are matched against your written authorisation, the approved script and the permitted contact channels before any agent is dispatched. Cases are grouped area-wise so every visit falls inside the 8:00 am to 7:00 pm window, and the 5-point repayment follow-ups record is fixed before allocation.

  2. 2

    On arrival

    Arrival, ID & permission

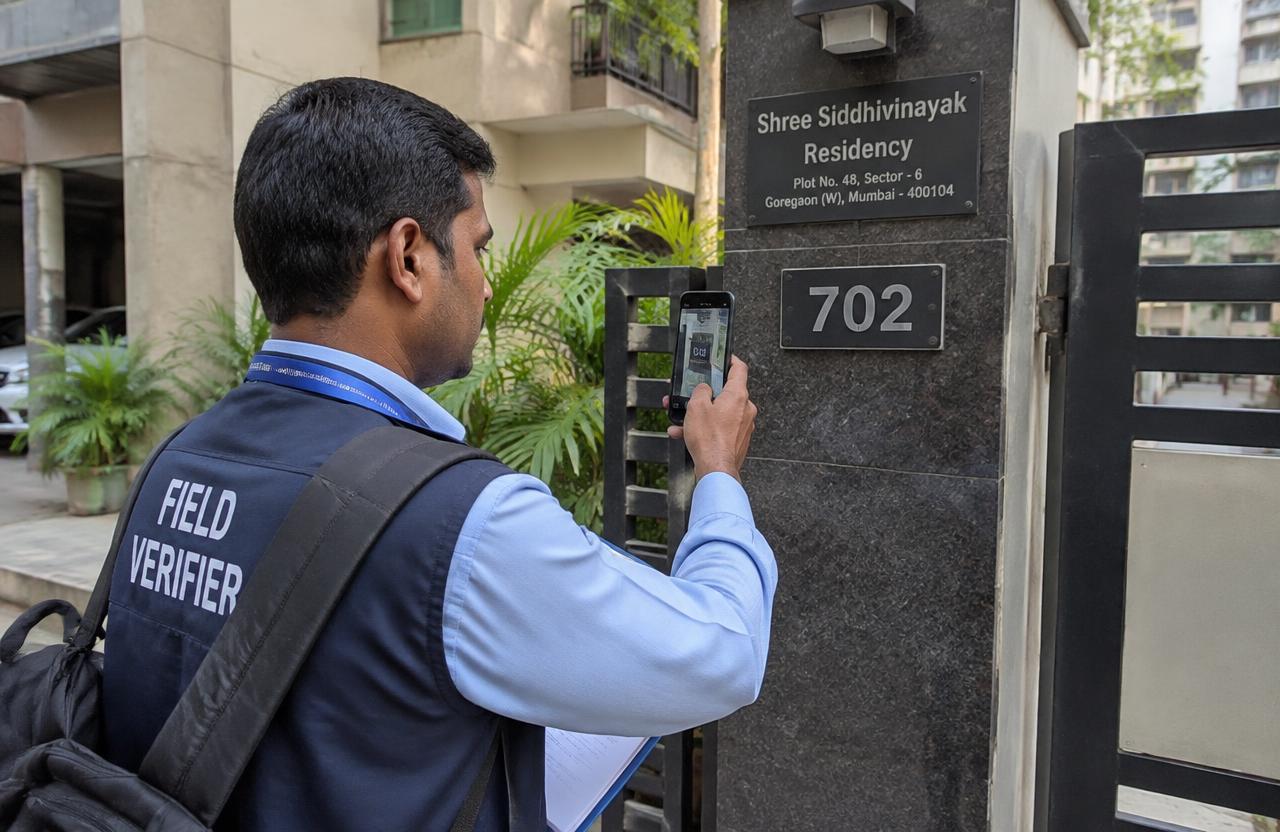
    The agent carries photo ID and your authorisation letter, identifies himself, states the purpose once and keeps to your approved script and communication channels. Language stays polite; there is no threat, intimidation or harassment, and third parties are approached only as far as your policy allows.

  3. 3

    On site

    Checklist & evidence capture

    All 5 checklist points are worked in order — "Due amount and date communicated" and "Reason for delay captured" among them — and each result is recorded against its item on the spot rather than from memory afterwards. The borrower's response and the reason given are written as stated, with the outcome coded to your disposition list.

  4. 4

    Close-out

    Acknowledgement & close-out

    Any commitment is noted with amount and date, and the borrower is pointed only to your approved payment channels — our team handles no cash unless you have specifically authorised it. Refusals, absences and shifted addresses are recorded with the reason instead of being left blank.

  5. 5

    Same day

    Supervisor review & submission

    Before anything reaches you, a supervisor checks the day's submissions for checklist completeness, evidence quality and correct coding, and random back-checks are run on a sample. Cleared work goes into your follow-up log in your approved format; anything that fails review goes back to the field.

Sample report

What a repayment follow-ups report looks like

Job / Location IDCase areaVisit date & timeChecklist resultEvidenceOutcome
FV-1042 / L-001Colaba, 400005Day 1, 10:305/5 items4 photosMet — commitment recorded
FV-1043 / L-002Byculla, 400027Day 2, 12:304/5 items3 photosNot available — revisit
FV-1044 / L-003Mahim, 400016Day 3, 14:303/5 items2 photosShifted — lead found

Illustrative format. Real reports follow your checklist and approved fields.

Evidence & quality

Evidence standard & quality controls

What is captured on the ground during repayment follow-ups, and the checks it passes before it reaches you — 5 checklist points and 4 report outputs per assignment.

Captured on every visit

  • Date, time and the name of the field agent logged against every case
  • Geo-tagged visit proof with the address visited, the person met and the disposition code used
  • Follow-up log — built from the field record, not retyped later
  • Response summary — built from the field record, not retyped later
  • Promise list — built from the field record, not retyped later
  • Escalation cases — built from the field record, not retyped later

Fields are limited to what your brief authorises — nothing extra is collected or stored.

Checked before it reaches you

  • Supervisor review of every submission — all 5 checklist points answered, with a reason recorded against anything marked not applicable
  • Random back-checks on a sample of completed visits by a second person
  • Conduct check against our Fair Practices Code — visiting hours, your approved script and the permitted payment channels
  • Exceptions kept separate from completed work, so your 4 report outputs show action items rather than silent gaps

Any row can be traced back to the original field record, so a query on one case is answerable without a fresh visit.

Checklist points
5 per case
Report outputs
4 — starting with follow-up log
Evidence type
Geo-tagged visit proof plus disposition code
Review
Supervisor check on every submission
Coverage
Mumbai, Thane, Navi Mumbai and Panvel
Visiting hours
8:00 am to 7:00 pm only

Commissioning triggers

Who commissions this / when it's triggered

Follow-ups work like repayment follow-ups is usually asked for at a specific moment, not on a calendar. These are the briefs we see most often.

01

Collections teams

A due date has passed

Your repayment request is communicated in the approved words, and the borrower's response and reason are recorded as given. A typical brief here is a 5-point repayment follow-ups round across Mumbai, Thane, Navi Mumbai and Panvel.
02

Recovery managers

A commitment was given and has to be tracked

The promise is logged with amount and date, a reminder is made before it falls due, and the kept-or-broken outcome is reported.

03

Operations & reconciliation

Borrowers say the payment has been made

Borrowers are directed only to your approved payment channels, proof of payment is requested, and receipt is confirmed with you.

  • Checklist point: Borrower response recorded
  • You receive: Follow-up log, Response summary, Promise list, Escalation cases
  • Covered: Mumbai, Thane, Navi Mumbai and Panvel

Industries that commission repayment follow-ups

Scope

What's in scope / what isn't

Stated plainly so the brief and the field report agree. Collections conduct follows the client's policy and our Fair Practices Code.

Included in a repayment follow-up assignment

  • The agreed repayment follow-up checklist worked point by point — Due amount and date communicated; Borrower response recorded
  • Each point recorded as found, including "Follow-up date set", with a reason noted wherever an item cannot be completed
  • Visits only for cases you have authorised in writing, using your approved script, contact rules and payment channels
  • Your report pack: Follow-up log, Response summary, Promise list, Escalation cases
  • Exceptions, refusals and inaccessible cases logged with the reason instead of being left blank
  • Supervisor review of every submission, with random back-checks on a sample of the completed work

Deliberately out of scope

  • No cash handling unless you have specifically authorised it — borrowers are directed to your approved payment channels
  • No visits or calls outside 8:00 am to 7:00 pm
  • No contact with third parties beyond what your policy allows
  • No legal advice, no notices of our own and no threat, intimidation or harassment of any kind
  • No case worked without your written authorisation, and no information collected beyond what the case requires

Conduct rules for every case are set out in our Fair Practices Code. Anything beyond this scope is added to the brief and authorised in writing before dispatch, never assumed in the field.

Frequently asked questions

What is repayment follow-ups?

Communicating the client's repayment request and recording the borrower's response. Our local field team handles it across Mumbai, Thane, Navi Mumbai and Panvel, and every submission is reviewed before it reaches you.

What do I need to share to start?

Case allocation file, Client authorisation letter, Approved communication script, Payment channel details.

What will the report include?

Follow-up log, Response summary, Promise list, Escalation cases.

How is repayment follow-ups priced?

Collections work is quoted separately after we review the assignment scope, case volume and geography.

Do your agents follow client rules?

Yes. Our Debt Recovery Agents work only on written client authorisation, use the client's approved communication and payment channels, and collect only the information the assignment requires.

Coverage · 76 localities

Repayment Follow-ups by location

Pick your area to see how Repayment Follow-ups is planned there — local landmarks, access notes and the nearby areas we can group into the same route.

Mumbai City

20 areas

South and central Mumbai — dense commercial districts, wholesale markets and corporate headquarters where visits are planned around traffic and building access rules.

Western Suburbs

15 areas

Bandra to Dahisar along the Western line — malls, high streets, studios and industrial estates covered by area-wise field teams.

Eastern Suburbs

12 areas

Kurla to Mulund along the Central and Harbour lines — malls, wholesale markets, IT parks and industrial belts.

Thane

9 areas

Thane city and the Ghodbunder corridor — townships, malls, industrial estates and dense residential markets.

Navi Mumbai

13 areas

Vashi to Ulwe — planned nodes, APMC markets, MIDC industrial belts and IT parks along the Thane–Belapur road.

Panvel

7 areas

Panvel, Kamothe, Kalamboli and Taloja — traditional markets, the steel market, MIDC units and new residential nodes.

Area not listed? We regularly travel just outside these boundaries — ask the desk and we'll confirm feasibility for your addresses.

Get a quote

Book repayment follow-ups in Mumbai, Thane, Navi Mumbai and Panvel

Name and phone are all we need to come back to you. Case-level information is shared later through a secure channel agreed during onboarding.

Planning a collections field assignment?

Share the scope — we'll come back with routes, timelines and a clear quote.

Start a collections enquiry
iPowered by IRPR